I should open by saying the Mr. FIRE and I keep our finances separate. This is pretty important to household harmony, because it means when I come home and find packages on the doorstep I can shrug my shoulders and think "when I'm retired and he heads into work on a Monday morning, I'm going to remind him of this." I'm a wonderful girlfriend aren't I?
One thing we do share is a FlyBuys account. Enter the case of the missing rewards points.
Sometime last year I was sent a promotion from FlyBuys telling me to switch my insurance to Medibank and earn FlyBuys points. After investigating their offerings I laughed and went back to my cheaper, lower cover with NIB. There is only so much health insurance I need at 26, and Australia has a pretty good health care system, so if I'm not covered by my private insurance I can just get treated in the public system. It takes longer but it costs next to nothing.
But Mr. FIRE is with Medibank on an old deal that they don't offer anymore. He had also just switched jobs and now his local supermarket was a Coles instead of a Woolworths. So with minimal badgering from me he set up a FlyBuys account linked to mine. Here's how that went down:
LadyFIRE: Here's my card - you should sign up. I think there's a bonus if we link our accounts. Plus we get points from the household bills and you pay those, so might as well link the accounts.
MrFIRE: K. *dutifully signs up like he was told"
some weeks later
MrFIRE: Hey, I've got like, 2,000 points.
LadyFIRE: That's odd, I've got heaps more than that. We must have separate points pools.
about a month ago
MrFIRE: Hey I've got a fair few points. What's the best way to spend them?
LadyFIRE: Dunno, I haven't really looked into it. I was just going to let them build up till I wanted something.
MrFIRE: Hmmm, well it's mostly crap like football merchandise, so I might just use it for money off shopping
LadyFIRE: Go your hardest, your points not mine.
late last night...
LadyFIRE: So hey... remember how I got you a flybuys account? and how our accounts are linked? You used all my points....
MrFIRE: I... ermm... wait... huh.... didn't we figure out that they appeared to be different pools?
LadyFIRE: Apparently not...
So yeah, that happened. Over the last month Mr. FIRE has quietly used up all my FlyBuys points getting $10 off a grocery shop each time.
On one hand, I know I shouldn't be that concerned. We've been sharing the account for a few months so he would have contributed a lot to the balance and the money was spent on groceries, which I've definitely been eating (yay food!). But, those were my points.
When I opened the account today I was looking to see if we could afford passes to the theme parks in Queensland. I was planning on suggesting we head up in a few months once the weather warmed up and check out the parks, and a few other attractions I have fond childhood memories of. Then I opened the account and saw a zero missing from the balance and my stomach sank.
Here I was, quietly hoarding points like a dragon on a pile of gold. I signed up for every offer, tried out different brands when they had a points special and religiously scanned my card for extra points. I'd been sitting on the points for years, apart from one budget crisis where I used them to cover my ass for a couple of weeks. They were a promise against a rainy day, and a vague dream of a holiday at some point. They were mine, I loved them, I cherished them... and he stole them!
Okay, so maybe I'm totally being melodramatic. The points were worth about $75 in groceries, or two 7-day park passes. Not a massive deal in the scheme of things, but I was so smug about those points, especially after I scored bonus points and $100 of free groceries with a sneaky credit card hack. I was pretty emotionally invested in those points.
It's given me a taste of how people must feel sharing a bank account with their partner, and opening it to see that after a big shop on shared necessaries the money is all gone. Some kind of resigned grumpy where you know it was 'fair' spending, but also totally not fair! It's that feeling of coming home and finding all the snacks are gone. Of having a warm blanket stolen in the middle of the night. Technically Mr. FIRE had as much right to (some of) those points as I did, but they were mine!
All I can say is thank god for not mixing bank accounts. I salute couples who can do that and maintain the harmony. As it is I'm making Mr. FIRE give me a massage since he 'stole' my points. I guess this works out well for me!
I'm on a quest for financial independence so I can retire early to the country with dogs, cows and an excellent glass of wine. Right now, I'm working in a concrete jungle. Tag along with me, it should be a great journey...
Friday, 28 April 2017
Friday, 21 April 2017
Money quotes you missed in pop culture
Did you know that popular culture is full of inspirational quotes about finances? They're hidden in plain sight. From Shakespeare, to Monty Python and back again, the world is full of pearls of wisdom, and I've collated some of the best, just for you. Have a read, your eyes will be opened, your horizons expanded. You will never view the world the same way again.
The Doctor: People assume that money is a strict progression of income to expenses, but actually, from a non-linear, non-subjective viewpoint, it's more like a big ball of wibbly wobbly... money-woney... stuff...
Kim Pine: [unenthusiastically] We are Sex Bob-omb. We are here to sell out and make money and stuff.
Dr. Vera Gorski: ...I want you to budget.
[Bjork's "Army of Me" playing over speakers]
Dr. Vera Gorski: ...
[Music stops]
Dr. Vera Gorski: If you do not budget you have no savings. And we don't keep things here that have no savings. You see, your fight for financial independence starts right now. You don't want to be judged? You won't be. You don't think you're strong enough? You are. You're afraid. Don't be. You have all the numbers you need. Now budget.
Hamlet: To spend, or not to spend- that is the question:
Whether 'tis nobler in the wallet to suffer
The costs and expenses of outrageous spending
Or to take arms against a sea of pointless consumerism,
And by opposing end them. To save- to invest-
Stewardess: Ladies and gentleman, this is your financial advisor speaking. We regret any inconvenience the sudden portfolio movement might have caused. This is due to periodic value corrections we encountered. There’s no reason to be alarmed and we hope you enjoy the rest of your investment journey. By the way, is there anyone on board who knows how to fly a plane?
Old Man from Scene 24: Stop! WHAT is your name?
King Arthur: It is Arthur, King of the Budgeters!
Old Man from Scene 24: WHAT is your quest?
King Arthur: To seek Financial Independence!
Old Man from Scene 24: WHAT is the airspeed velocity of an unladen swallow?
King Arthur: What do you mean? African or European swallow?
Old Man from Scene 24: I, I don't know that! *gets pulled to the sky and thrown down the Gorge of Eternal Debt*
Sir Bedevere: How do you know so much about swallows?
King Arthur: Well, you have to know these things when you're king, y'know.
Brian's mother: He's not the Financially Literate. He's a very naughty boy! Now, piss off!
“My name is Inigo Montoya, you budget poorly, prepare to die!”
Narrator: FI. the final frontier. These are the voyages of the moneyship Enterprise. Its five-year mission: to explore strange new investments, to seek out new income and new financial habits, to boldly go where no man has gone before.
Mal: "I swear by my pretty floral bonnet, I will invest."
So you see, financial quotes are everywhere if you keep your eyes and ears open! What's your favourite finance quote?
The Doctor: People assume that money is a strict progression of income to expenses, but actually, from a non-linear, non-subjective viewpoint, it's more like a big ball of wibbly wobbly... money-woney... stuff...
Kim Pine: [unenthusiastically] We are Sex Bob-omb. We are here to sell out and make money and stuff.
Dr. Vera Gorski: ...I want you to budget.
[Bjork's "Army of Me" playing over speakers]
Dr. Vera Gorski: ...
[Music stops]
Dr. Vera Gorski: If you do not budget you have no savings. And we don't keep things here that have no savings. You see, your fight for financial independence starts right now. You don't want to be judged? You won't be. You don't think you're strong enough? You are. You're afraid. Don't be. You have all the numbers you need. Now budget.
Hamlet: To spend, or not to spend- that is the question:
Whether 'tis nobler in the wallet to suffer
The costs and expenses of outrageous spending
Or to take arms against a sea of pointless consumerism,
And by opposing end them. To save- to invest-
Stewardess: Ladies and gentleman, this is your financial advisor speaking. We regret any inconvenience the sudden portfolio movement might have caused. This is due to periodic value corrections we encountered. There’s no reason to be alarmed and we hope you enjoy the rest of your investment journey. By the way, is there anyone on board who knows how to fly a plane?
Old Man from Scene 24: Stop! WHAT is your name?
King Arthur: It is Arthur, King of the Budgeters!
Old Man from Scene 24: WHAT is your quest?
King Arthur: To seek Financial Independence!
Old Man from Scene 24: WHAT is the airspeed velocity of an unladen swallow?
King Arthur: What do you mean? African or European swallow?
Old Man from Scene 24: I, I don't know that! *gets pulled to the sky and thrown down the Gorge of Eternal Debt*
Sir Bedevere: How do you know so much about swallows?
King Arthur: Well, you have to know these things when you're king, y'know.
Brian's mother: He's not the Financially Literate. He's a very naughty boy! Now, piss off!
“My name is Inigo Montoya, you budget poorly, prepare to die!”
Narrator: FI. the final frontier. These are the voyages of the moneyship Enterprise. Its five-year mission: to explore strange new investments, to seek out new income and new financial habits, to boldly go where no man has gone before.
Mal: "I swear by my pretty floral bonnet, I will invest."
So you see, financial quotes are everywhere if you keep your eyes and ears open! What's your favourite finance quote?
Monday, 17 April 2017
Saving is boring! Stay on track
Alright guys, I have a confession to make. I am bored of savings. Putting aside $20k for my emergency fund is easily the most dull and meaningless savings goal I've ever had. I love investing, pushing money into accounts that fund my retirement is thrilling. I've had to slow that down to save for my emergency fund and I'm bored.
So I prowled the internet for some tips. While there are plenty on ways to change your saving / spending habits, finding ways to stay motivated was harder.
Let me start by saying that I haven't held more than $10,000 in cash since I discovered that I could invest. At first I thought the money on a high interest account was exciting and at 18 I had something like $30,000 in my account earning 6% (from memory). At the time it was great, but then interest rates dropped and I discovered shares and bonds. The first set of bonds I bought were paying 8.7%. From that moment I was hooked, I kept $5,000 in my account for 'emergencies' and every time I hit $10,000 I pushed half of it into an investment.
That system worked for me for years, until I refinanced my home loans and forgot I had to pay for my renovations on my rental property. I had approximately $15,000 free in those home loans, then I refinanced and had nothing. Then the renovation bills came in for $10,000. Oh, and I was about to go on three weeks unpaid leave. In short it was monumentally stupid.
I scraped through on a combination of credit cards and goodwill (renovations went on a payment plan, Mr. FIRE picked up the slack). I managed not to pay any interest on the credit cards but it was a close deal, in some cases by a day or two. So I understand the value of having an emergency fund with six months worth of expenses, but it's just, so, boring.
Firstly, it's a pun, so this is clearly the best trick. Get it, account-able? Oh never mind, it's a bad pun... I have filled my life with ways to keep this goal in the fore-front of my mind. I have a giant multi-page google spreadsheet that tracks my spending. I have another one on my home computer that tracks and charts my savings. I have this blog. I have a note pinned on the side of my computer (It also tells me to buy an investment property and renovate my bathroom before the end of the year). I have this blog. Writing about this goal is keeping me interested in it. And it stops me from throwing the whole thing out the window and investing, just, it's a close thing...
I also have charts, I love charts!
Of course, you'd have to pay for Amy's designs, which is probably not the greatest move if you're swimming in debt, even if they are only $20. You can buy a whole book of kaleidoscope patterns for $2, but then you have to count all the spaces and decide how you're going to represent each savings goal on it. Or you can just start one from scratch on your own.
Grab a sheet of paper, decide what appeals to you, how you're going to colour it as you go and sketch away. You'll be far more invested if you drew the progress map yourself, and you can make it the right size for your needs. Plus if you're savings for a house, you can colour in an actual house, rather than something abstract.
I have to admit though, I absolutely suck at art. As much as this is a super cool idea, i don't think it's for me.
Combining my love of board games and conventional motivational wisdom I have just come up with this idea on the fly. Turns out most motivational information on the internet is abstract and boring. Here's what I've just thrown together for myself to get through the last couple of months.
So I prowled the internet for some tips. While there are plenty on ways to change your saving / spending habits, finding ways to stay motivated was harder.
Let me start by saying that I haven't held more than $10,000 in cash since I discovered that I could invest. At first I thought the money on a high interest account was exciting and at 18 I had something like $30,000 in my account earning 6% (from memory). At the time it was great, but then interest rates dropped and I discovered shares and bonds. The first set of bonds I bought were paying 8.7%. From that moment I was hooked, I kept $5,000 in my account for 'emergencies' and every time I hit $10,000 I pushed half of it into an investment.
That system worked for me for years, until I refinanced my home loans and forgot I had to pay for my renovations on my rental property. I had approximately $15,000 free in those home loans, then I refinanced and had nothing. Then the renovation bills came in for $10,000. Oh, and I was about to go on three weeks unpaid leave. In short it was monumentally stupid.
I scraped through on a combination of credit cards and goodwill (renovations went on a payment plan, Mr. FIRE picked up the slack). I managed not to pay any interest on the credit cards but it was a close deal, in some cases by a day or two. So I understand the value of having an emergency fund with six months worth of expenses, but it's just, so, boring.
Stay accountable
![]() |
| My 2016 savings chart The green line is total of all accounts, the black line was my target. |
I also have charts, I love charts!
Colour me rich
With the surge in popularity of adult colouring books it's not surprising that someone figured out how to link colouring to their savings goals. Amy Jones has even kicked off an online business devoted to colouring in bit by bit to track her progress. She sells really cool progress maps that you can download, print off, stick to a wall and colour in bit by bit as you march towards your goal.Of course, you'd have to pay for Amy's designs, which is probably not the greatest move if you're swimming in debt, even if they are only $20. You can buy a whole book of kaleidoscope patterns for $2, but then you have to count all the spaces and decide how you're going to represent each savings goal on it. Or you can just start one from scratch on your own.
Grab a sheet of paper, decide what appeals to you, how you're going to colour it as you go and sketch away. You'll be far more invested if you drew the progress map yourself, and you can make it the right size for your needs. Plus if you're savings for a house, you can colour in an actual house, rather than something abstract.
I have to admit though, I absolutely suck at art. As much as this is a super cool idea, i don't think it's for me.
Roll six for rewards
Combining my love of board games and conventional motivational wisdom I have just come up with this idea on the fly. Turns out most motivational information on the internet is abstract and boring. Here's what I've just thrown together for myself to get through the last couple of months.So, here's how it works. At each goal point ($13,000, $15,000, $17,000 and $19,000) I roll two dice. The dice on the left tells me what reward table I get to use. 1-3 is a boozy reward, 4-5 is a fancy dinner, and six is both! The next dice then tells me what reward I get. So in the picture I've rolled a five (fancy dinner) and a three. So I get to have roast for dinner! As dinners go it's on the more expensive scale, especially compared to our usual meals like Chilli Con Carne, so we don't have it too often, but it is delicious!
To be honest though, I really want nachos for dinner, so I might give myself the right to re-roll each dice once when picking rewards, haha, oops! Since I record my current savings once a week, I should have plenty of chances to get some tasty rewards!
What works for you? How do you stay on track for these long drawn out goals. Savings takes time, are you straying off track?
Tuesday, 11 April 2017
Another way of looking at 'cost' (and a Chilli Con Carne recipe)
It's not a secret that I like money. I like having it, I like investing it. I'd like to have enough of it invested that the invested money makes enough money to cover my living costs. Then I can stop trading time for money. Time is pretty finite, I can't earn more of that.
Most Early Retirement blogs will tell you the process is simple, earn more, spend less, invest the difference. Then the negative comments on those blogs will try and tell you that spending $5 less per day isn't going to make you a millionaire, or significantly delay your retirement. It took me a while to really cut into the heart of this, but there are a few ways of looking at your expenses, and what they really cost you.
If you want to retire on the income from your investments, that income needs to cover your ongoing costs, plus covering inflation. Most financial gurus will accept that you can (reasonably) safely withdraw 4% of the value of your portfolio each year and stay ahead of the game. This assumes that your portfolio is continuing to grow through reinvested dividends.
Now - what we have is a $5p/day ($1,825) expense that needs to be covered by your portfolio. You can only withdraw 4% of your portfolio, so therefore your portfolio needs to be 25x that expense to cover it (that 25x comes from 100/4). So to cover a $5 per day expense, which is costing you $1,825 actual dollars per year, you need $45,625 invested to cover that $5 a day. The Australian Bureau of Statistics says that in November 2014 the average full time salary was 76k per year. That means you would need to invest 60% of a years income just to cover a $5 a day habit (probably take-away coffee).
Is a daily coffee really worth $45k to you? Cause it definitely isn't to me. But another perspective is the food budget. Currently my food budget is $6.50 per day (plus whatever Mr. FIRE spends), which means investing $60k to cover my food expenses. $6.50 per day averages $2.15 per meal. I can make Chilli Con Carne for $1.15 per serve.
Of course, I don't eat that cheap every night. Some nights we have steak and chips, for about $6-$7 (good steak is pricey!). For one meal it's barely $5 difference, but if we were to eat that way every meal we could easily need another $100,000 just to maintain our lifestyle. A few nights of delicious budget chilli con carne brings our early retirement much closer.
Most Early Retirement blogs will tell you the process is simple, earn more, spend less, invest the difference. Then the negative comments on those blogs will try and tell you that spending $5 less per day isn't going to make you a millionaire, or significantly delay your retirement. It took me a while to really cut into the heart of this, but there are a few ways of looking at your expenses, and what they really cost you.
Number 1: The actual cost per week/month/year
This is pretty obvious, and it's the first on that people think of. $5 per day is $35 per week, $150 per month, or $1,825 per year. Put that way it doesn't really seem like much.Number 2: The ten year value of that money if you invested it
This is the number that Mr Money Mustache always tells people to consider. Assuming 7% interest (which is a viable number, stop being so negative!):- to calculate a weekly expense compounded over ten years, multiply the price by 752
- for a monthly expense, multiply by 173
Number 3: The amount of money you would have to invest to cover that $5 per day.
This is my favourite way of looking at the long-term cost. It's also the best because I didn't directly steal it from someone else. I'm sure other people look at on-going costs this way, but I've never seen it formally written, so here I go.If you want to retire on the income from your investments, that income needs to cover your ongoing costs, plus covering inflation. Most financial gurus will accept that you can (reasonably) safely withdraw 4% of the value of your portfolio each year and stay ahead of the game. This assumes that your portfolio is continuing to grow through reinvested dividends.
Now - what we have is a $5p/day ($1,825) expense that needs to be covered by your portfolio. You can only withdraw 4% of your portfolio, so therefore your portfolio needs to be 25x that expense to cover it (that 25x comes from 100/4). So to cover a $5 per day expense, which is costing you $1,825 actual dollars per year, you need $45,625 invested to cover that $5 a day. The Australian Bureau of Statistics says that in November 2014 the average full time salary was 76k per year. That means you would need to invest 60% of a years income just to cover a $5 a day habit (probably take-away coffee).
Is a daily coffee really worth $45k to you? Cause it definitely isn't to me. But another perspective is the food budget. Currently my food budget is $6.50 per day (plus whatever Mr. FIRE spends), which means investing $60k to cover my food expenses. $6.50 per day averages $2.15 per meal. I can make Chilli Con Carne for $1.15 per serve.
Of course, I don't eat that cheap every night. Some nights we have steak and chips, for about $6-$7 (good steak is pricey!). For one meal it's barely $5 difference, but if we were to eat that way every meal we could easily need another $100,000 just to maintain our lifestyle. A few nights of delicious budget chilli con carne brings our early retirement much closer.
Chilli Con Carne
This recipe made me 20 serves.Ingredients
- 1 tbsp oil
- 1 large onion
- 1 red pepper
- 2 garlic cloves, peeled
- 1 heaped tsp hot chilli powder (or 1/2 level tbsp if you only have mild)
- 1 tsp paprika
- 1 tsp ground cumin
- 500g lean minced beef
- 1 beef stock cube
- 400g can chopped tomatoes
- 1/2 tsp dried marjoram
- 1 tsp sugar
- 2 tbsp tomato purée
- 200g dried red kidney beans
- 5 cups (uncooked) rice
Method
- Cook your kidney beans the day before. Boil for 10minutes, then toss in a slow cooker for about 5 hours.
- Put your pot on over a medium heat. Add the oil and leave it for 1-2 minutes until hot. Add the diced onions and cook, stirring, for about 5 minutes, or until the onions are soft, squidgy and slightly translucent. While the onion is cooking slice open red peppers, discard the seeds and dice.
- Add the garlic, red pepper, chilli powder, paprika and ground cumin to the pot. Give it a good stir, then leave it to cook for another 5 minutes, stirring occasionally.
- Brown the beef. Turn the heat up a bit, add the meat to the pot and break it up with your spoon or spatula. The mix should sizzle a bit when you add the mince. Keep stirring and prodding for at least 5 minutes, until all the mince is in uniform, mince-sized lumps and there are no more pink bits. Make sure you keep the heat hot enough for the meat to fry and become brown, rather than just stew.
- Crumble beef stock into 600ml hot water. Pour this into the pan with the mince mixture. Open the can of chopped tomatoes and add these as well. Tip in marjoram and sugar, if using, and add a good shake of salt and pepper. Squirt in tomato purée and stir the sauce well.
- Simmer it gently. Bring the whole thing to the boil, give it a good stir and put a lid on the pan. Turn down the heat until it is gently bubbling and leave it for 20 minutes. You should check on the pan occasionally to stir it and make sure the sauce doesn’t catch on the bottom of the pan or isn’t drying out. If it is, add a couple of tablespoons of water and make sure that the heat really is low enough. After simmering gently, the saucy mince mixture should look thick, moist and juicy.
- Bring on the beans. Rinse red kidney beans in a sieve if you haven't already and stir them into the chilli pot. Bring to the boil again, and gently bubble without the lid for another 10 minutes, adding a little more water if it looks too dry. Now replace the lid, turn off the heat and leave your chilli to stand for 10 minutes before serving, and relax. Leaving your chilli to stand is really important as it allows the flavours to mingle.
- Serve with rice. To get the $1.15 per serve value I served 2 scoops of rice with 1 scoop of Chilli Con Carne.
Friday, 7 April 2017
DTF: dollars to fun ratio
What is your DTF rule? Do you have a pretty loose DTF ratio? Or are you super tight when it comes to DTF?
No, I'm not talking about the Urban Dictionary definition, I mean the Dollars To Fun ratio.
As part of the Financial Independence and frugality movement, I think a lot about the value of my spending. Does buying the expensive name brand bread increase my happiness enough to justify the extra dollar on the price tag when compared to the sad floppy home brand stuff (Hint, it totally does).
There is a huge difference between cost and value. Cost is what you pay for it. Value is what you get from it. Put simply, a loaf of bread costs me $3.40. I value it because I'm hungry, and it goes well with soup. When it comes to the DTF ratio, I use it to consider whether the cost of something is worth the value I got out of it. Specifically, I use the DTF ratio to look at entertainment.
Before I stumbled across this whacko idea of retiring early, I would look at home much I earned per hour and I decided that I would pay about half that for an hours entertainment. I should probably clarify that this was back when I was living at home and I could afford to blow every dollar I made. This rule worked out great for me! Movies for $10 fit well within the DTF rule. I could buy a video game at $80 because it was easily going to consume every night for a few weeks. Gigs met the DTF rule because I had to listen to all the music before I went to the live show (yes, even factoring in the cost of the album, it was still DTF-approved).
Thankfully this hasn't come through to my adult life, but for many people it has. That motorbike I'll hardly ever ride is $2,000 but I make $100,000+ so it's DTF-approved. A yacht spends most of it's time tied up at the dock, but I'm rich so DTF. I've had a lousy day at work earning $30 an hour and these shoes are only $50 and so cute, DTF!!
Consumer spending has got to be the number one cause of debt in Western society. We are constantly advertised at and told we deserve bigger more expensive things. In my quest for FIRE I have tried to move away from this.
My ideal Dollars To Fun ratio is a mere $1 an hour. For $1 an hour I'm DTF.
Amazingly, a dollar an hour goes a really really long way. Mr. FIRE and I went fishing on the weekend. We spent $7 on bait and spent five hours down at the seashore. We would have had dinner from it but it turns out we need to learn to fillet properly, but my hens got a good feed of fish scraps!
A dollar an hour pays for most books of the Amazon Kindle store. Assuming you read them more than once, and don't buy books the day they are released. My favourite author has a new book out for $17.99, but the one she released last year is a mere $6.99. By employing the magic skill of waiting, I can have the book and still meet the DTF ratio.
Video games used to be my biggest wealth thief. A new release console game sells for around $80 to $100. Despite the hours of game play they swear they have, most games fizzle out for me around 20-30 hours, and then the cost of buying the console on top of that means that I don't buy or play as many games anymore. However I still play all my old games, some of which have over 200 hours play time across two or three different play through.
According to Steam my most played game is The Sims3 (I'm not proud of that) for 68 hours. I bought it for $12. On the other hand my library is full of pointless games that I paid a dollar or two for and only played for 10 minutes. Even worse is the collection of games I bought in a bundle and never touched. Frugal fail.
Of course, not everything can be bought for a dollar an hour. I love rock-climbing. I play roller derby. I've been wearing a True Grit wristband for years even though I've only been on two events (I should really take that off...) These things weren't even close to meeting the DTF rule. Rock climbing is about $5 an hour, plus gear costs. Derby is $80 a month for 24 hours worth of training. Rather than berate and guilt myself for these 'expensive' pleasures, I simply crowd out other expenses with low cost activities.
I might spend $80 a month on roller derby, but slacklining is free (apart from the initial purchase of the line). Fishing was $7 for two people for a few hours, hiking is free and if you know what you're doing both of them give you a chance to pick up a free dinner.
In my quest for financial independence, if the balance is right, I'm always DTF.
Thanks for letting me write a blog entirely devoted to DTF. I'm looking forward to the google traffic for this one! Leave a comment and let me know what you consider a fair price for entertainment.
No, I'm not talking about the Urban Dictionary definition, I mean the Dollars To Fun ratio.
As part of the Financial Independence and frugality movement, I think a lot about the value of my spending. Does buying the expensive name brand bread increase my happiness enough to justify the extra dollar on the price tag when compared to the sad floppy home brand stuff (Hint, it totally does).
There is a huge difference between cost and value. Cost is what you pay for it. Value is what you get from it. Put simply, a loaf of bread costs me $3.40. I value it because I'm hungry, and it goes well with soup. When it comes to the DTF ratio, I use it to consider whether the cost of something is worth the value I got out of it. Specifically, I use the DTF ratio to look at entertainment.
Before I stumbled across this whacko idea of retiring early, I would look at home much I earned per hour and I decided that I would pay about half that for an hours entertainment. I should probably clarify that this was back when I was living at home and I could afford to blow every dollar I made. This rule worked out great for me! Movies for $10 fit well within the DTF rule. I could buy a video game at $80 because it was easily going to consume every night for a few weeks. Gigs met the DTF rule because I had to listen to all the music before I went to the live show (yes, even factoring in the cost of the album, it was still DTF-approved).
Thankfully this hasn't come through to my adult life, but for many people it has. That motorbike I'll hardly ever ride is $2,000 but I make $100,000+ so it's DTF-approved. A yacht spends most of it's time tied up at the dock, but I'm rich so DTF. I've had a lousy day at work earning $30 an hour and these shoes are only $50 and so cute, DTF!!
Consumer spending has got to be the number one cause of debt in Western society. We are constantly advertised at and told we deserve bigger more expensive things. In my quest for FIRE I have tried to move away from this.
My ideal Dollars To Fun ratio is a mere $1 an hour. For $1 an hour I'm DTF.
Amazingly, a dollar an hour goes a really really long way. Mr. FIRE and I went fishing on the weekend. We spent $7 on bait and spent five hours down at the seashore. We would have had dinner from it but it turns out we need to learn to fillet properly, but my hens got a good feed of fish scraps!
A dollar an hour pays for most books of the Amazon Kindle store. Assuming you read them more than once, and don't buy books the day they are released. My favourite author has a new book out for $17.99, but the one she released last year is a mere $6.99. By employing the magic skill of waiting, I can have the book and still meet the DTF ratio.
Video games used to be my biggest wealth thief. A new release console game sells for around $80 to $100. Despite the hours of game play they swear they have, most games fizzle out for me around 20-30 hours, and then the cost of buying the console on top of that means that I don't buy or play as many games anymore. However I still play all my old games, some of which have over 200 hours play time across two or three different play through.
According to Steam my most played game is The Sims3 (I'm not proud of that) for 68 hours. I bought it for $12. On the other hand my library is full of pointless games that I paid a dollar or two for and only played for 10 minutes. Even worse is the collection of games I bought in a bundle and never touched. Frugal fail.
Of course, not everything can be bought for a dollar an hour. I love rock-climbing. I play roller derby. I've been wearing a True Grit wristband for years even though I've only been on two events (I should really take that off...) These things weren't even close to meeting the DTF rule. Rock climbing is about $5 an hour, plus gear costs. Derby is $80 a month for 24 hours worth of training. Rather than berate and guilt myself for these 'expensive' pleasures, I simply crowd out other expenses with low cost activities.
I might spend $80 a month on roller derby, but slacklining is free (apart from the initial purchase of the line). Fishing was $7 for two people for a few hours, hiking is free and if you know what you're doing both of them give you a chance to pick up a free dinner.
In my quest for financial independence, if the balance is right, I'm always DTF.
Thanks for letting me write a blog entirely devoted to DTF. I'm looking forward to the google traffic for this one! Leave a comment and let me know what you consider a fair price for entertainment.
Tuesday, 4 April 2017
Goals Update: March 2017
All in all, this has been a pretty great month! For the first time I actually feel like I might be able to hit my target.
Next month I'm actually going to record what I do and what day. I don't feel like I'm achieving this goal, so I need a bit more transparency on it.
Grade: C
Grade: A+
Disclaimer: I'm definitely calculating my returns in a weird way. Current Value divided by Amount Invested equals Overall Return. The number is then adjusted to be annual. It means if I dump in a huge sum of money my return appears to go down. Therefore the return quoted here is a conservative number and I'm okay with that.
Gas and Electricity bills this month. And we're over by less than $30, so I'm calling that a massive win! Bring on a bill free month.
If we go with the place we're looking at I'll be putting in $230 a fortnight towards this property once it's settled. In theory it will be slightly cashflow negative at the beginning (about $10 a week). Mr. FIRE and I have agreed to put money towards it as if everything went wrong and we were bleeding money. That way we'll have a buffer and pay down our mortgage faster.
The average is low because I upgraded my health insurance to include hospital cover in January. So the average is reflecting the old, lower cover and will steadily come up across the year.
On the plus side, derby has been consistently cheaper than I expected so I've shaved a bit out of this budget. Let's see how that turns out.
I am so proud of me! I had a massage, I bought some beers, I generally had a wonderful month and I spent absolutely bugger all on it! By making a list of things that I want I've been able to feel like I'm progressing towards having them and appeasing my immediate "I want" reflex, but I haven't spent on those things and I don't miss not having them. The list is working well!
Mike and I also went out fishing! Watch this space for a blog about it, but for $7 worth of bait we spent 5 hours on the beach. We went as the tide was coming in and fish where everywhere! Unfortunately they were all little ones so we only brought one home. Then we discovered that we need to learn how to fillet properly. After completely stuffing it up, we ended up throwing the entire fish to the hens, woops!
Offset Balance: $8,450.54
Owing on Credit Cards: $1,720.78
Total: $11,804.82
Increase from last month: $3,069.20
Amount remaining: $8,195.18 (approx $2,731 a month)
I finally saved more in a month than I needed! Finally. I'm less excited than I should be though because I need to pull off the same trick three more times, and there will be bills. I'm also lining up to buy another property (detailed post to come, I promise) which will mean a whole new layer of expenses. Yes there will be income, but there will be all the purchase expenses up front.
It also goes to show what procrastination can do to you. If I had stuck to the path back in December I only needed to save $2,100 a month, 36% of my income. After a couple of unexpected costs and not watching my spending I'm up to needing to save $2,731, or 46% of my income. I can't go back and change what I've done but I can sigh, shake my head at myself and push to do better.
Check out this handy-dandy chart to see how well I'm (not) doing.
Check out the history of this goal:
Do physical fun stuff 4x a week
It's been a hard month. I got my new weights, and immediately did some damage to my left thigh. After getting an ACL reconstruction last year it means that both of my knees hurt now. At 26, urgh. It's not the best feeling. I've been skating a bit more than in past months and went out slack-lining a couple of times. I still haven't gotten back out rock-climbing since derby came back, but I did go fishing once!Next month I'm actually going to record what I do and what day. I don't feel like I'm achieving this goal, so I need a bit more transparency on it.
Grade: C
Create something each month
Ermm, no. I launched a Facebook group for this blog and I've seen a massive spike in readers (690 views in February, 1,800 in March) but I haven't created anything else. I guess the blog counts as a creative outlet, and I love doing it, but it doesn't have the same satisfaction as building something new like my superannuation calculator, the million dollar calculator, or building a new chicken coop.
Grade: C
Apply for one freelance task a week
Finally some success! I wrote four short articles and made $29.60. I've also got another article in the pipeline that I'll be paid $16 for.Grade: A+
And now, the money!
Here we goMarch Totals
Income
| Salary | $4129.98 |
| Sidegigs | $7 |
| Home | $600 |
| Investment Property #1 | $1097.30 |
| Investment Property #2 | $0 |
| Cash Dividends | $83.50 |
| Total | $5,896.54 |
Salary
Nothing exciting here. I work, I get paid.Side gigs
I made $29.60USD on UpWork, but I haven't cashed it out yet, so I haven't listed it here. UpWork charges a flat fee every time you cash out, so I like to do it in bigger chunks. I made $7 from selling eggs though! Pets that make a profit are wonderful!
Home
I bought home entirely in my name, but my partner lives here. He pays half of all the bills, plus $300 a fortnight in rent. Pretty sweet deal.Investment property #1
A standard month.
Investment property #2
*gasp* Oh my, where did that come from!? Well, technically it doesn't exist yet. But I have some expenses for going out researching, so I added the zero income - watch this space! Although with settlements being over a month don't expect anything too soon.
Dividends
Trucking along nicely. I have some bonds that will be redeemed next month and I'll have an extra $5k to play with, you can weigh in on what I should do with it in an earlier post.Investment performance
| Deposit | Reinvested Dividends | Annual Return | |
| RateSetter | $100 | $84.78 | 5.72% |
| ASX | $0 | $0 | 5.71% |
| Vanguard | $400 | $0 | 4.61% |
| Acorns | $24.15 | $0.03 | 8.45% |
Expenses
| Spent | Budgeted | Annual Average | |
| Home | $1,279.89 | $1,250 | $1,319.95 (down $2.14) |
| Investment Property #1 | $909.39 | $1,250 | $1.613.60 (down $82.86) |
| Investment Property #2 | $598.73 | $600 | $49.89 (up $49.89) |
| Personal Bills | $140.60 | $147.08 | $102.68 (up $6.30) |
| Groceries | $102.30 | $200 | $183.26 (down $11.83) |
| Pets | $44.69 | $30 | $21.67 (up $3.72) |
| Derby | $97.26 | $100 | $78.51 (up $3.94) |
| Travel | $0 | $108 | $131.19 (no change) |
| Other | $46.94 | $250 | $533.51 (down $10.03) |
| Total | $3,219.80 | $4,026 | $4,034.26 (down $42.63) |
Home (Over $28.89)
Gas and Electricity bills this month. And we're over by less than $30, so I'm calling that a massive win! Bring on a bill free month.Investment Property #1 (Under $340.61)
Just one bill for the annual insurance.Investment Property #2 (Over $1.27)
Woah, where did this come from! Mr. FIRE and I have been working with a property coach for a few months and we hopped a plane on Saturday to do some research in Melbourne. I might have something super interesting to share soon...If we go with the place we're looking at I'll be putting in $230 a fortnight towards this property once it's settled. In theory it will be slightly cashflow negative at the beginning (about $10 a week). Mr. FIRE and I have agreed to put money towards it as if everything went wrong and we were bleeding money. That way we'll have a buffer and pay down our mortgage faster.
Personal Bills (Under $6.40)
This is my phone bill and health insurance, it should never change - except it did! My premiums went up on my insurance this year, an extra 7.5%. Huge increase and still the best on the market, hey at least I'm not living in America! I've upped the annual budget in this one to account for the change in premiums that start next month. Urgh.The average is low because I upgraded my health insurance to include hospital cover in January. So the average is reflecting the old, lower cover and will steadily come up across the year.
Groceries (Under $97.70)
We're riding on the coat tails of a big stock up last month and using credit card rewards I bought $125 of groceries for a mere $25. Thanks giant supermarket chain, I'll happily take those freebies you're offering!Pets (Over $14.69)
I bought $35 worth of chicken pellets which should last a couple of months and Mr. FIRE paid for a round of cat food. After tracking this properly for a few month I can see that $25 a month was far too low and I've upped the budget to $30 a month.Derby (Under $2.74)
Dues and I booked my return flight from Queensland for TWELVE DOLLARS! Hell yeah! Paired with my $40 flight there I am thrilled with all the credit card rewards I've been able to take advantage of. I spent $4 at the second hand store on a striped shirt because the proper uniform I ordered still hadn't arrived when I needed it!On the plus side, derby has been consistently cheaper than I expected so I've shaved a bit out of this budget. Let's see how that turns out.
Travel (Under $108)
No travel, no spend. Easy peasy :) Any travel for derby is counted in the derby category. The average isn't dropping because I also spent nothing this month last year.Other (Under a massive $203.06)
$4 on a friends birthday. Good start! $70 on a massage and $10 on beers, but I got a $50 rebate on my credit card that went towards the massage. I also spent $6 on a gorgeous pair of tights second hand that probably would have sold for $30+ when they were new.I am so proud of me! I had a massage, I bought some beers, I generally had a wonderful month and I spent absolutely bugger all on it! By making a list of things that I want I've been able to feel like I'm progressing towards having them and appeasing my immediate "I want" reflex, but I haven't spent on those things and I don't miss not having them. The list is working well!
Mike and I also went out fishing! Watch this space for a blog about it, but for $7 worth of bait we spent 5 hours on the beach. We went as the tide was coming in and fish where everywhere! Unfortunately they were all little ones so we only brought one home. Then we discovered that we need to learn how to fillet properly. After completely stuffing it up, we ended up throwing the entire fish to the hens, woops!
Savings Goal
High Interest: $5,075.06Offset Balance: $8,450.54
Owing on Credit Cards: $1,720.78
Total: $11,804.82
Increase from last month: $3,069.20
Amount remaining: $8,195.18 (approx $2,731 a month)
I finally saved more in a month than I needed! Finally. I'm less excited than I should be though because I need to pull off the same trick three more times, and there will be bills. I'm also lining up to buy another property (detailed post to come, I promise) which will mean a whole new layer of expenses. Yes there will be income, but there will be all the purchase expenses up front.
It also goes to show what procrastination can do to you. If I had stuck to the path back in December I only needed to save $2,100 a month, 36% of my income. After a couple of unexpected costs and not watching my spending I'm up to needing to save $2,731, or 46% of my income. I can't go back and change what I've done but I can sigh, shake my head at myself and push to do better.
Check out this handy-dandy chart to see how well I'm (not) doing.
Check out the history of this goal:
- December 2016 - $6,992.39
- January 2017 - $7,088.91
- February 2017 - $8,735.62
Friday, 31 March 2017
What's your earliest money memory?
Remember this blissful ignorance of youth? When food magically appeared, mounds of toys were gifted every Christmas and birthday and you wanted for nothing? Then at some point you discovered 'money' and things were never the same. Suddenly those toys had a cost, but if you had money you had the power to buy things!
Sometimes discovering money is wonderful, sometimes it's not. I asked some of my favourite bloggers what their earliest Money Memory was, and how it shaped their path to Financial Independence.
My sister and I both got a very generous $5 weekly allowance. At first I spent my entire allowance each week on candy and cheap toys. However, one day my eyes spied a beautiful My Little Pony doll. But alas! The toy was $10 and I only had my meager $5. It wasn't until this very moment that I realized I could save money until next week to buy something nicer.
I remember walking out of K-Mart with my $5 in my hand, vowing to return later for the My Little Pony. My mom was so perplexed that I didn't buy anything. I explained that I'd rather save my money and buy one nice thing instead of blowing it each week on small things. She realized I learned what it meant to save, so then I got my $20 monthly allowance upfront from that point on.
At the time I didn't think anything of it, but this was genius on my parents' part! I got to learn money lessons on a small scale while I was young and I learned the importance of saving.
For my 5th birthday, my parents bought me a Radio Flyer wagon. I had wanted one for a long time and I was filled with joy when I laid eyes on it. I took it outside and hauled my toy tractors around for the entire afternoon.
That evening, I forgot to put it away and the next morning, it was gone. Someone had stolen it. I didn't even have it for 24 hours. When I realized what had happened, I cried. Then, I asked my parents for another new one. Their response was a firm 'No' along with a lecture of how I shouldn’t have been so careless. They also let me know that my dad worked hard to at his job to buy me the wagon.
It was on that day that I connected work, money and stuff. That I still remember the ordeal clearly 38 years later reminds of how powerful that lesson was.
The Little Red Bank
For Christmas when I was 6 or 7, someone gave me a little bank that looked like a old-time cash register.
You'd deposit a coin into it and pull the lever. The bank kept a running total of money you deposited. The catch was that the bank wouldn't open until you saved $10.
At first, owning the bank was infuriating to my little child brain. $10 seemed like a fortune and it angered me that I couldn't get the money out whenever I wanted. I remember it usually took me months to accumulate $10. One time, I even tried to smash it open.
However, a funny thing happened when I saved the $10 and my money was liberated; I didn't spend it. I like to think that the bank made me appreciate the money.
Bordering on the line of legality, I had downloaded to a few $5 apps ("games" in those days) on my dad's work phone, unaware that they were indeed subscription based and he would also be charged $5 for the 'Welcome' text, $5 for the 'Unsubscribe' text, and $5 for each daily text. That added up pretty quick. To be honest, after he found out, I considered myself lucky to still be alive.
I was a kid so I had no way to pay that bill. My parents barely had the money themselves, and I wish I hadn't put that kind of financial stress on them.
The only thing I was good for was chores, so that's how I paid them back. For the next 3 years, I washed and dried the dishes after every meal for the whole family. I did this 365 days a year until I moved out.
There was so much guilt over what I'd done. I had offered to empty my bank account to put towards the bill but my parents refused. That money, $500, is what I moved to the city with, I used to set up my life here and to build what I have today.
When I got a phone of my own, I made sure it was pre-paid, and I have learned not to waste money quite so liberally.
LadyFIRE note: Mrs. ETT sent this through to me saying "This was an interesting exercise. I tried to think of some positive stories, but honestly couldn't remember anything." I think it's super valuable to include 'negative' memories like these to highlight that not everyone has pleasant money memories, but we can rise above them. Thanks for sharing Mrs. ETT!
I ended up asking my dad about shares and he explained them to me, showing me how to track the prices in the newspaper. Fast forward a number of years and I now have my very own share portfolio. I don't keep the information in a leather bound portfolio, but I am thankful for the introduction Thomas provided me all those years ago.
A huge thank you to all the bloggers who responded. I'm super chuffed to have superstars like Mr 1500 and J. Money here! Leave a comment and tell me your earliest money memory, and who I should reach out to next time!
Sometimes discovering money is wonderful, sometimes it's not. I asked some of my favourite bloggers what their earliest Money Memory was, and how it shaped their path to Financial Independence.
LadyFIRE - Me!
My earliest money memory is checking my bank statement in March. I couldn't tell you what year, but I distinctly remember it being March. I got a three month statement for the high interest account my parents had set up. There would have been a couple of hundred dollars in there, and this is back when accounts were earning a lot more than they are now, so maybe 6% or 7%. We'll say 6.5% for the sake of argument. I remember reading how much interest I earned, in December it was $1.10. In January, $1.10. In February 99 cents.
Only 99 cents? Outrage! The banks were ripping me off! My dad sat me down and I learnt that banks pay interest daily, and since February only had 28 days it paid less than December and January. It definitely got me hooked on the idea of Free Money.
I still check my interest payments religiously to this day. I love being rewarded for leaving my money alone for a month.
Although I didn't know things were tight, I was naturally frugal. I had a piggy bank and saved loose change I found while using metal detectors with my dad. But my earliest money memory happened on the aisles of K-Mart. Only 99 cents? Outrage! The banks were ripping me off! My dad sat me down and I learnt that banks pay interest daily, and since February only had 28 days it paid less than December and January. It definitely got me hooked on the idea of Free Money.
I still check my interest payments religiously to this day. I love being rewarded for leaving my money alone for a month.
Mrs. Picky Pincher from Picky Pinchers
My parents never talked about money in front of my sister and I. We didn't have much money when I was a little kid, so I suspect they kept us sheltered from a lot of tough conversations.My sister and I both got a very generous $5 weekly allowance. At first I spent my entire allowance each week on candy and cheap toys. However, one day my eyes spied a beautiful My Little Pony doll. But alas! The toy was $10 and I only had my meager $5. It wasn't until this very moment that I realized I could save money until next week to buy something nicer.
I remember walking out of K-Mart with my $5 in my hand, vowing to return later for the My Little Pony. My mom was so perplexed that I didn't buy anything. I explained that I'd rather save my money and buy one nice thing instead of blowing it each week on small things. She realized I learned what it meant to save, so then I got my $20 monthly allowance upfront from that point on.
At the time I didn't think anything of it, but this was genius on my parents' part! I got to learn money lessons on a small scale while I was young and I learned the importance of saving.
1500 Days to Freedom
Learning the Value of Money through a Big Red Wagon and a Little Red Bank
The Big Red WagonThat evening, I forgot to put it away and the next morning, it was gone. Someone had stolen it. I didn't even have it for 24 hours. When I realized what had happened, I cried. Then, I asked my parents for another new one. Their response was a firm 'No' along with a lecture of how I shouldn’t have been so careless. They also let me know that my dad worked hard to at his job to buy me the wagon.
It was on that day that I connected work, money and stuff. That I still remember the ordeal clearly 38 years later reminds of how powerful that lesson was.
The Little Red Bank
For Christmas when I was 6 or 7, someone gave me a little bank that looked like a old-time cash register.You'd deposit a coin into it and pull the lever. The bank kept a running total of money you deposited. The catch was that the bank wouldn't open until you saved $10.
At first, owning the bank was infuriating to my little child brain. $10 seemed like a fortune and it angered me that I couldn't get the money out whenever I wanted. I remember it usually took me months to accumulate $10. One time, I even tried to smash it open.
However, a funny thing happened when I saved the $10 and my money was liberated; I didn't spend it. I like to think that the bank made me appreciate the money.
J. Money from Budgets are Sexy
My earliest money memory was probably getting an allowance of a whopping $1.00 a week growing up. I'm sure my parents tried teaching me before that, but nothing puts things in perspective until you're holding cold hard cash in your hands :) I learned fast just how expensive all those things I wanted were, and even more so how important prioritizing is. Things went from costing "only $10.00" to "only 10 weeks of allowances" which completely changes your mindset! And all of a sudden I didn't want as much as I used to ;)The Wealthy Bogan
When I was 14 I managed to rack up a gigantic phone bill. "Are you 18+?" they would ask. Absolutely I am, now let me download things.Bordering on the line of legality, I had downloaded to a few $5 apps ("games" in those days) on my dad's work phone, unaware that they were indeed subscription based and he would also be charged $5 for the 'Welcome' text, $5 for the 'Unsubscribe' text, and $5 for each daily text. That added up pretty quick. To be honest, after he found out, I considered myself lucky to still be alive.
I was a kid so I had no way to pay that bill. My parents barely had the money themselves, and I wish I hadn't put that kind of financial stress on them.
The only thing I was good for was chores, so that's how I paid them back. For the next 3 years, I washed and dried the dishes after every meal for the whole family. I did this 365 days a year until I moved out.
There was so much guilt over what I'd done. I had offered to empty my bank account to put towards the bill but my parents refused. That money, $500, is what I moved to the city with, I used to set up my life here and to build what I have today.
When I got a phone of my own, I made sure it was pre-paid, and I have learned not to waste money quite so liberally.
Mrs. ETT from Enough Time To...
I have two early money memories, and both unfortunately have negative connotations. When we went on excursions in primary school, we were allowed to take some pocket money to buy something. I remember coming home from a day at the museum with some gemstone chips from the shop, along with my change. My mum berated me because I hadn’t bought home any presents for the family - “you used to be so generous.” I didn’t remember being generous, but I guess it must have been around that time that I became careful with money, which sees me as a natural saver today (Mr. ETT used to comment about moths flying from my wallet when I open it!). My other memory of that time is when mum and dad had to take some money out of the bank. I can’t remember what for, but I do remember excitedly asking to see it in the foyer of the bank once it was withdrawn, and being shushed quite emphatically. It was later they explained to me that it could be dangerous for people to know we are walking around with a lot of cash. That taught me that money was not something to be talked about, and that maybe we were lucky to have money that others didn’t have. Today, left to my own devices, I would keep as much as my money locked away as I could. Luckily, I have Mr. ETT to balance me, and encourage me to spend when it is important, just like mum was looking for."LadyFIRE note: Mrs. ETT sent this through to me saying "This was an interesting exercise. I tried to think of some positive stories, but honestly couldn't remember anything." I think it's super valuable to include 'negative' memories like these to highlight that not everyone has pleasant money memories, but we can rise above them. Thanks for sharing Mrs. ETT!
Adventures with Poopsie
When I was in grade two, a boy in my class named Thomas told me that he had a share portfolio. I probed a little deeper and it turned out, his dad had started each of his son's a share portfolio when they were born. I thought this was amazing! I didn't know what a share portfolio was, but I imagined that he had a leather bound portfolio that he kept safe at home. I imagined this little seven year old boy walking around with his portfolio, and I knew I wanted one too!I ended up asking my dad about shares and he explained them to me, showing me how to track the prices in the newspaper. Fast forward a number of years and I now have my very own share portfolio. I don't keep the information in a leather bound portfolio, but I am thankful for the introduction Thomas provided me all those years ago.
A huge thank you to all the bloggers who responded. I'm super chuffed to have superstars like Mr 1500 and J. Money here! Leave a comment and tell me your earliest money memory, and who I should reach out to next time!
Saturday, 25 March 2017
Eggscellent pets: Frugal and flavourful!
Check out these beautiful ladies. Tempest, Ethyl and their (unpictured) sister Wookie have been keeping me rolling in eggs for almost three years now. I've owned chicken since late high-school and they are some of the greatest animals in the world. On top of producing eggs daily, they dispose of any food scrap you can think of (except onions and citrus fruits) are solely responsible for the eggscellent soil in my veggie path, and are just so darn adorable.
Chickens make brilliant additions to a frugal backyard because on top of actually making you breakfast (well, you still need to cook) they can be the most self-reliant pets you forgot you had, or they can be lap chickens up for a snuggle.
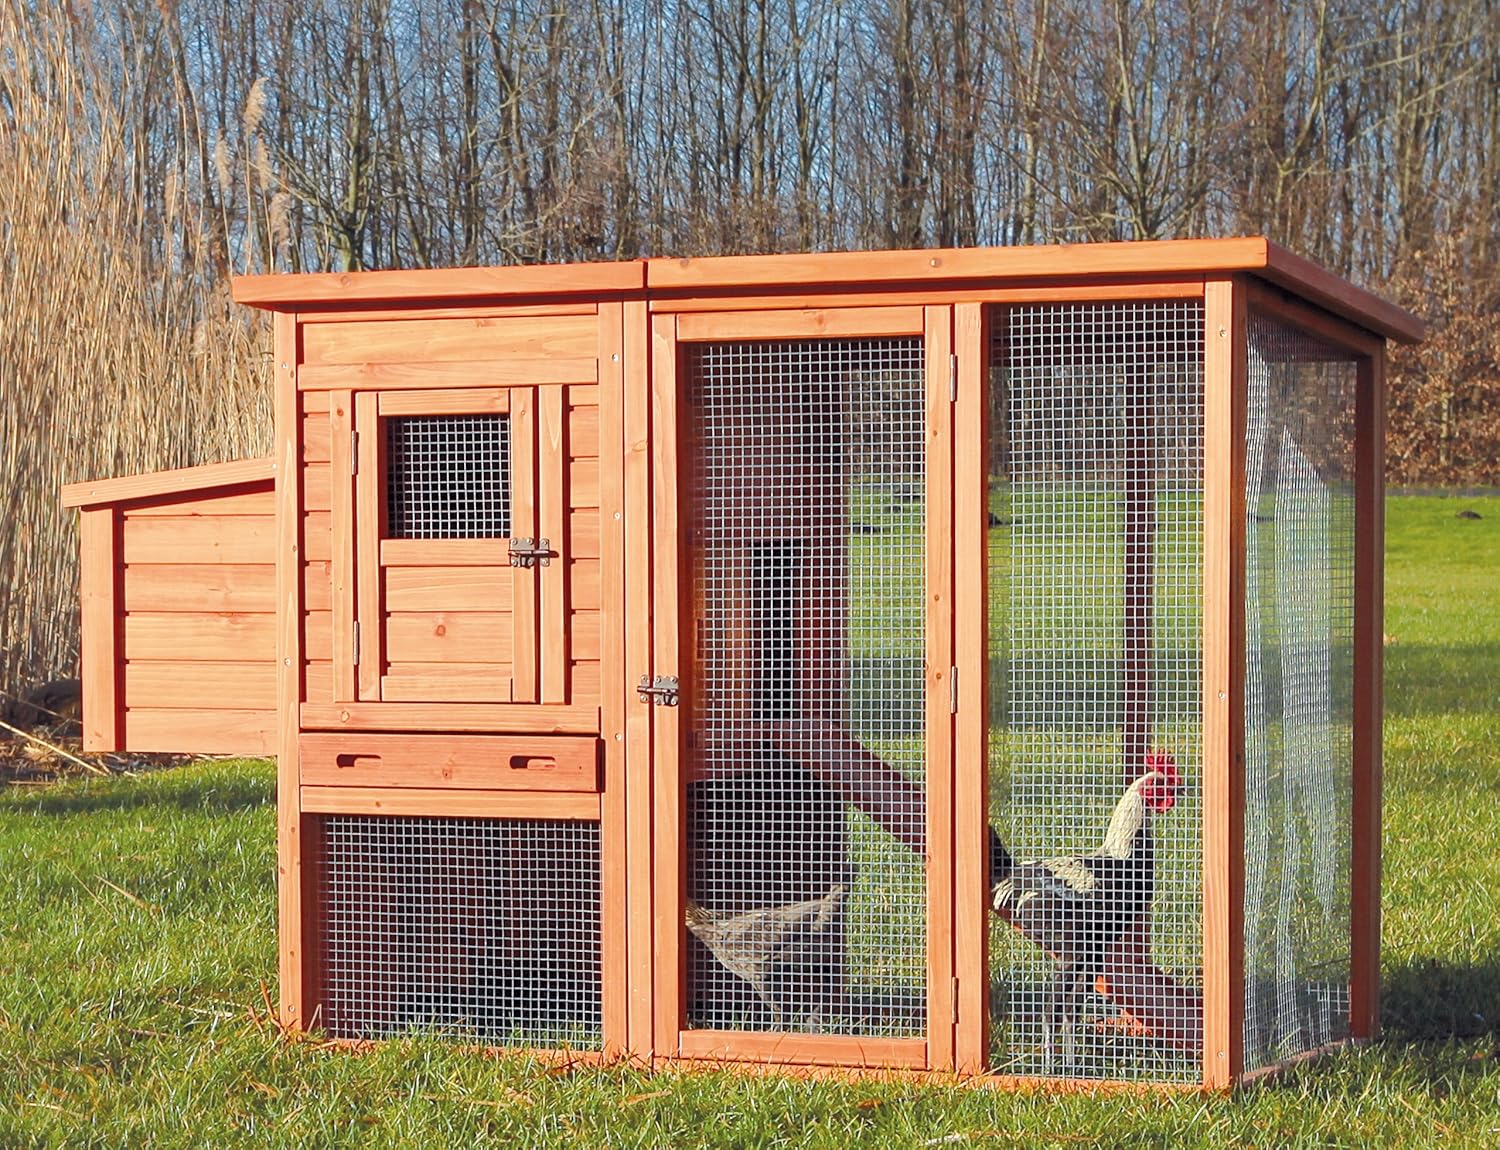
Well, if you're in a hurry, you can buy this bad boy for $195. Mr. FIRE and I were in a rush, so this is what our ladies live in. The floor has rusted through, the door fell off and I've had to cover the sides and put an extra perch up. It was a terrible purchase, but our old coop was falling down. Plus it is FAR too small for even two hens to live in full-time. It's an acceptable overnighter if your hens will be free ranging, but if not you need to build a run.
For a frugal solution, keep an eye on hard rubbish, Gumtree and listen in on your friends getting rid of scrap wood! You can pull together something much more effective (and cheaper!) for a third of the price with some basic woodworking skills. Mr. FIRE and I will be replacing our coop in the coming year and plan to build it from scratch.

There are so many eggs I can't find enough ways to use them all. I have zuchinni slice, cake, banana bread, eggs and rice, bacon and eggs, quiche and yet somehow I still have dozens of eggs left over! Thankfully my area has a thriving trade culture and I've swapped a dozen eggs for close to $10 worth of produce (hello Kale!) as well as being able to sell a dozen eggs for $3 or $4. I'm not sure if I'll make back the cost of the expensive but cheaply made coop I bought online, but as far as cashflow goes, the hens sit in the plus column!
Chickens make brilliant additions to a frugal backyard because on top of actually making you breakfast (well, you still need to cook) they can be the most self-reliant pets you forgot you had, or they can be lap chickens up for a snuggle.
Getting started - the expensive bit
To get started with chickens you don't need much space, but you do need security. Chickens are silly little featherheads that will fly over a fence and parade in front of a doberman if they see something snacky. Or if they're startled by a falling leaf. Or if the sun is the wrong shade of red. Honestly if they can jump a fence and find something dangerous they probably will. Your first month with hens will be coming home to find poop across the back porch and a thirsty, hungry bird will run up to you begging to be saved. They won't run close enough to easily be picked up and popped back in the pen, but they will come running nonetheless.
Coops, roosting and nesting
Thankfully, hens aren't that big or strong, so once you get some decent fencing in place, you'll have them safely contained. First you need a coop. That's the indoors bit with solid walls. Sometimes.
| You definitely don't need to be this fancy, but it looks great! |
There's a variety of wisdom about the benefits of four solid walls (for warmth) versus three walls and an open side (for ventilation) or some combination of the two. Personally I have three full walls with a small gap along the top, and a half wall with a small gap at the top, and a chicken-height gap at the bottom. I also leave the door open at all times because I'm in a built-up, suburban, fox-free area (fingers crossed, touch wood!). If you live in a rural area, or near a nature reserve you'll either need to close up the coop at night, or ensure the run is fox-proof.
Firstly, the interior of the coop. Each hen needs a minimum of 40cm perch space. But since hens constantly squabble with one another, I recommend 1 perch for a pair, 2 perches for 3-6 hens, and 3 perches if you have more, with enough length for an extra bird (i.e. for 3 hens, you would need 2 perches and 160cm of space). Make sure the perches are more than pecking distance apart or you will have two grouchy birds taking over all the perches, and the rest sleeping on the floor in their own poop. Yuck.
Chickens are also ground birds, their feet are more suited to walking than gripping branches, so use wide flat perches. Roosts are for sleeping, so you want your birds as comfortable as possible.
![]() |
| DIY coops can be gorgeous! Pro-tip, you don't need to be this good. The hens won't know it's ugly! Source |
Next, you need a nest box, that's where the eggs go (hopefully). Nest boxes are tricky to plan. You want them at least the width of your hen so she can fit comfortably, but not so big she feels like she's out in the open. We have 2 boxes side by side that are 45cm cubed (roughly). You should always have at least two nest boxes, with roughly one box for every 4-5 hens. But they will inevitably choose their favourite one or two and always lay there, hens have been known to line up!
Runs, for diggin' scratchin' and good times!
This bit is easier - hens need at least one square metre of space each. Obviously that is a really really tiny space, so you're flock should get 2-3 square metres to start with, plus their one each, plus the space inside the coop. Anything less and you will end up with fat, grumpy hens who will constantly squabble. If you have a small yard, build a moveable run, then you can pick two plots of land and alternate them between chicken yard and pre-fertilised veggie garden!
If you have dogs, or live in an area with foxes use hardware mesh (not chicken wire) to build your fence, and bury it at least 50cm deep. If like me, you're in a 'safe' area (touch wood again!) you can use bird netting strung between garden stakes and weighed down at the bottom,
So what does it cost?

For a frugal solution, keep an eye on hard rubbish, Gumtree and listen in on your friends getting rid of scrap wood! You can pull together something much more effective (and cheaper!) for a third of the price with some basic woodworking skills. Mr. FIRE and I will be replacing our coop in the coming year and plan to build it from scratch.
Our run is currently made from a length of bird netting ($20) and garden stakes and old bricks we had lying around. Our ladies live under an apple tree, so they're protected from the elements and I think they ate more apples this year than we did!
And finally, you have to buy then hens themselves, unless you're lucky enough to find one walking down the road. That's how Wookie came into our lives. You can order a half dozen day-old fresh out of the shell hens for around $2-3 each if you find a nearby farmer. Commercial stores will sell them for more, but that's convenience for you! Day old hens require heat, special food, carefully stocked water and a whole lot of other trickiness. However you can buy fully fledged hens (ready for the great outdoors) from $6 - $25. The younger they are, the cheaper, however you have to shell out for food until the freeloaders hit laying age around 18weeks.
Life with chickens
Okay, now that we've gone through all the drama of set up and your hens have arrived (and you've chased them back into the pen a hundred times and plugged all the holes in the fence) you can settle down and enjoy them. Hens are generally quiet unless they've laid an egg and want to brag about it. The worst I've had was fifteen minutes of the 'egg song' at around 8am. More often than not, your neighbours will be surprised to find out you have hens, they're so quiet.
If you want to handle your hens, they will do anything for food. Start as soon as they come home, and hand feed them kitchen scraps, budgie seeds, weeds you pulled from the footpath. Soon they will know you've got the good stuff and come running when they see you.
In terms of food and water - make a top fill dispenser to ensure they always have pellets available (our pellets cost about $35 for 2 and a bit months) and fresh water at all times. The more kitchen scraps they eat, the less pellets you'll use. You can build brilliant DIY feeders with a few lengths of PVC pipe - simply grab a 180degree elbow, about a metre of pipe about 20cm diameter and a cap and glue the lot together. For the food pipe, leave the cap loose so you can fill from the top. For the water, glue the cap on, then fill by flipping upside down. Water will flow down until the level sits higher than the bend and will sit there like a vacuum seal, similar to putting your finger over the end of a straw.
Finally, start collecting junk mail (without any plastic gloss) old newspapers and bills. You don't need to buy straw to line the nest boxes, simple fill with shredded paperwork and change every week or two.
And you're done! Enjoy free eggs for the rest of your life! You can up the care quality by regularly providing treats (watching hens fight over spaghetti is amazing) and checking for mites and bugs, but with access to a good amount of fresh dirt, hens are largely self-sufficient.
Notice I've been saying hens this whole time? Because roosters are LOUD! Technically they are great for flock dynamics and will keep the ladies in line, protect them from cats and announce the good food. But they are so so very loud, from the first tiny glimmers of sunshine two hours BEFORE dawn to that last breath of sunset they don't stop. It's not just the crowing, but the incessant chatter. Unless you are rural and want the baby chooks or perhaps to make Coq au Vin, steer clear of roosters, no matter how pretty.
Makin' a little on the side
So far our hypothetical hens have cost us about $250 in housing, and $18 a month in food. But they give back an average egg every 2 days. In summer they'll lay daily, and in winter when the days are shorter they'll slow down and take a break. My three hens are eating $18 worth of food a month, and giving back almost five dozen eggs! To buy five dozen cheap, ethically questionable eggs would cost me $21, to buy free-range eggs would be $31.50!
Except that time they escaped and ate all my peas... right down to the ground.
Tell me about your pets! What do they cost in dollars? What do they add to your life that makes them completely worth it? Bonus points for photos!
Tuesday, 21 March 2017
Ratesetter: Peer-to-Peer Lending
Have you ever looked at the huge fees and interest rates that personal lenders charge and thought 'damn, I wish I could be on that side of the equation'. While banks and credit unions are offering us a piddly 3% interest rate on 'bonus' saver accounts, they are charging 13-20%. Someone is making a killing there, and it's not me.
Enter RateSetter, where you can be the lender and reap the profits.
Basic concept
RateSetter and other peer-to-peer lending companies act as the middle man between you and someone who wants to take out a loan. Personal lending is rife with risks, what if they don't pay you back? What if you lose a friend over this? What if you don't lend them the money and you lose a friend for refusing to 'help'? My favourite author Patrick Rothfuss used the phrase "There are two sure ways to lose a friend one is to borrow, the other is to lend", or for a classic version from Shakespeare himself, "Neither a borrower nor a lender be; For loan oft loses both itself and friend."
RateSetter place themselves as a middle man between you and the borrower. This creates a lovely layer of protection between you and the borrower (you could be lending to your mother and you'd never know!) as well as opening up a huge pool of borrowers for you.
You can get started for as little as $10 which almost matches the minimum Acorns investment of $5. RateSetter doesn't have a nice mobile app like Acorns does, but it exposes you to a different market and (in my experience) has far better returns.
RateSetter place themselves as a middle man between you and the borrower. This creates a lovely layer of protection between you and the borrower (you could be lending to your mother and you'd never know!) as well as opening up a huge pool of borrowers for you.
You can get started for as little as $10 which almost matches the minimum Acorns investment of $5. RateSetter doesn't have a nice mobile app like Acorns does, but it exposes you to a different market and (in my experience) has far better returns.
Pros: Easy to start, easy to use, low fees
RateSetter has a slightly tricky menu that could do with some better labels, but you'll get your head around it in about five or ten minutes. They give you a variety a ways to deposit funds, either by RateSetter pinging your account using POLi payments, or you can use BPAY to send money across. I haven't used POLi, but BPAY deposits are generally processed within 48hours.
Once your funds arrive, you jump over to the lending tab and pick your market. You can lend for 1 month, 1 year, 3 years or 5 years. In the 1 month market you receive all your investment plus some interest back at the end of the month, generally for a rate around 3.5 - 4%. In the one year market you receive small interest payments throughout the year, and you investment back as a lump sum at the end. One year markets generally have a rate of around 5%. Honestly, neither of these offer enough return to be worth using in my opinion.
RateSetter shines in the three and five years markets. Each payment returns a small around of your principal, plus an interest payment (just like when paying off your own mortgage). The three year market is currently offering 8.4%, and the five year market is at 8.7%, though it tends to hover closer to 9 or even 10%.
The fees are quite reasonable - RateSetter takes 10% of your earnings, rounded down. That sounds like a lot, but when weighed against a 9% return, it works out really well. e.g. lend $1,000 at 9%, that's $90 a year. You get $81, RateSetter takes $9. You have still made 8.1% on your investment. But also, because you can deal in teeny tiny $10 loans, and their cut is rounded down, I quite often have an interest payment of 7 or 8 cents, which RateSetter won't take any of. In my February goals update RateSetter made me $78, 2% of my financial independence needs!
Next up in brilliant features is the reinvestment settings. By ticking a couple of boxes (that you can change anytime) you can ask for all repayments to be automatically reinvested for the length of time your choose at either market rate, or your set rate. If you set a rate and the current market rate is higher, your funds will be invested at that higher rate. You can also split it by loan term ,so your 1month loans can cycle endlessly in the 1 month market while building a separate nest-egg in the five year market.
And finally, RateSetter has a provision fund. Fees collected from borrowers are stored in the provision fund so in the unlikely event that a borrower defaults you can claim back your initial investment. Unfortunately the provision fund won't pay any missed interest, but in eight years of business RateSetter has not lost a single dollar. That's a wonderful track record!
Once your funds arrive, you jump over to the lending tab and pick your market. You can lend for 1 month, 1 year, 3 years or 5 years. In the 1 month market you receive all your investment plus some interest back at the end of the month, generally for a rate around 3.5 - 4%. In the one year market you receive small interest payments throughout the year, and you investment back as a lump sum at the end. One year markets generally have a rate of around 5%. Honestly, neither of these offer enough return to be worth using in my opinion.
RateSetter shines in the three and five years markets. Each payment returns a small around of your principal, plus an interest payment (just like when paying off your own mortgage). The three year market is currently offering 8.4%, and the five year market is at 8.7%, though it tends to hover closer to 9 or even 10%.
The fees are quite reasonable - RateSetter takes 10% of your earnings, rounded down. That sounds like a lot, but when weighed against a 9% return, it works out really well. e.g. lend $1,000 at 9%, that's $90 a year. You get $81, RateSetter takes $9. You have still made 8.1% on your investment. But also, because you can deal in teeny tiny $10 loans, and their cut is rounded down, I quite often have an interest payment of 7 or 8 cents, which RateSetter won't take any of. In my February goals update RateSetter made me $78, 2% of my financial independence needs!
Next up in brilliant features is the reinvestment settings. By ticking a couple of boxes (that you can change anytime) you can ask for all repayments to be automatically reinvested for the length of time your choose at either market rate, or your set rate. If you set a rate and the current market rate is higher, your funds will be invested at that higher rate. You can also split it by loan term ,so your 1month loans can cycle endlessly in the 1 month market while building a separate nest-egg in the five year market.
And finally, RateSetter has a provision fund. Fees collected from borrowers are stored in the provision fund so in the unlikely event that a borrower defaults you can claim back your initial investment. Unfortunately the provision fund won't pay any missed interest, but in eight years of business RateSetter has not lost a single dollar. That's a wonderful track record!
Cons: Medium risk, locked in funds
Okay, I've gushed about how much I love RateSetter, let me talk about the things that are less than perfect.
Lending money is risky. This isn't like a term deposit where the bank is super solid and there are government checks and balances to protect you. This is a company who has promised to protect you, but they are a business, and you are a lender. Loans sometimes default, it's a fact. So peer-to-peer lending falls into the Medium risk category. Some might say high, but the track record and provision fund make me willing to call it Medium.
Next, the terms. Your money is locked away for five years. It's a pain in the proverbial. When I started I was using all four markets for variety, before realising I much preferred the five year terms and started switching my money over. I started using RateSetter in November 2014, I changed to only lending in the five year market in March 2015. I still have money stuck in the three year market. And it's there for another year. Stuck because of a choice I made two years ago. No getting rich quick with RateSetter, just a long slow build. On the upside though, once you hit FIRE, you can change your reinvestment settings to reinvest your principal and pay out the interest to you. Easy cash flow for your retirement income!
And finally, the one little thing that offends my delicate sensibilities. RateSetter's biggest business is car loans. Mr FIRE and I are a one car family (with four bikes!) and scoff at people who take out car loans! But I guess I should be grateful that their financial choices are funding my retirement!
RateSetter are currently offering a $75 sign-up bonus if you invest $2,000 before the 15th of April. This referral link will also give me $75 (thanks) but will only work for me five times. If you chose to sign up, you will get your own referral link to share with your friends.
RateSetter aren't currently offering any sign up bonuses, but that doesn't minimise their appeal to me. After fees, I'm earning more than 9% per annum, and after four years I can honestly say I am very happy with my investment.
Lending money is risky. This isn't like a term deposit where the bank is super solid and there are government checks and balances to protect you. This is a company who has promised to protect you, but they are a business, and you are a lender. Loans sometimes default, it's a fact. So peer-to-peer lending falls into the Medium risk category. Some might say high, but the track record and provision fund make me willing to call it Medium.
Next, the terms. Your money is locked away for five years. It's a pain in the proverbial. When I started I was using all four markets for variety, before realising I much preferred the five year terms and started switching my money over. I started using RateSetter in November 2014, I changed to only lending in the five year market in March 2015. I still have money stuck in the three year market. And it's there for another year. Stuck because of a choice I made two years ago. No getting rich quick with RateSetter, just a long slow build. On the upside though, once you hit FIRE, you can change your reinvestment settings to reinvest your principal and pay out the interest to you. Easy cash flow for your retirement income!
And finally, the one little thing that offends my delicate sensibilities. RateSetter's biggest business is car loans. Mr FIRE and I are a one car family (with four bikes!) and scoff at people who take out car loans! But I guess I should be grateful that their financial choices are funding my retirement!
RateSetter aren't currently offering any sign up bonuses, but that doesn't minimise their appeal to me. After fees, I'm earning more than 9% per annum, and after four years I can honestly say I am very happy with my investment.
Links to RateSetter are referral links. If you have any experience with peer-to-peer lending, I'd love to hear your story!
Friday, 17 March 2017
Where should I put a windfall? Tell me what you think
I have an unexpected 'windfall' coming my way. I purchased $5,000 worth of bonds that were listed to last until 2074. Given the current low interest rates a lot of companies have been paying out these bonds and opening new ones with much lower interest rates. It's good business for them, but it means they're closing my investment and I'm about to have $5,000 in my pocket. I have some ideas what I want to do with it, but I'd love to hear your opinion.
I could drop the money into my Acorns account and dramatically decrease the percentage I'm paying in admin fees. My highest performing investment is in peer-to-peer lending (review to come!) but I have more than 20% of my non-real estate investment there already and I think that might be a bit risky, even if the 9.5%+ return is lovely.
I could also use it to balance my Vanguard portfolio, or I could dig in a bit more research and purchase some strong performing dividends shares, or another set of bonds.
If I get the time, I'd love to think about this more. But I'm also super aware of Warren Buffets advice that boils down to "If you don't know what you're doing, toss it in a low cost index fund like Vanguard and leave it there forever".
According to the stats on this blog close to 100 people drop by every day, most of you come from other personal finance blogs. I'd love to hear what you think (and verify that my stats aren't entirely robots!). The money hits my account on the 31st of March - what should I do with it?
Option 0: A neeeeeeeeeeeeeeeew car!
Hahaha, kidding. I had to throw this in here. There is no way the money is getting spent on anything but buying back my free time.
Option 1: Put it towards the savings goal
This is the obvious option, I've got a goal to reach $20,000 in savings by the first of July (check my last update for February) but honestly that feels like cheating. The goal was to save $20,000, not to pull it out of my investments and put it into my savings account.
Option 2: Pay down some of the mortgage
This is an oldie but a goodie. Unexpected money can always be put towards mortgages, and the way mine are set up any excess payments can be withdrawn later free of charge. But it's not the best use of the money, the bonds were earning 5.05% and the mortgage is only costing me 3.99%. It'd be a net loss of 1% interest each year.Option 3: Invest! But where?
This is where I'm headed! Invest! But where? The money is coming out of bonds with one of the Big 4 banks. Should I put it back into the same place, or somewhere different? The bank is offering reinvestment in their new bonds, but they pay about the same as my mortgage is charging.I could drop the money into my Acorns account and dramatically decrease the percentage I'm paying in admin fees. My highest performing investment is in peer-to-peer lending (review to come!) but I have more than 20% of my non-real estate investment there already and I think that might be a bit risky, even if the 9.5%+ return is lovely.
I could also use it to balance my Vanguard portfolio, or I could dig in a bit more research and purchase some strong performing dividends shares, or another set of bonds.
If I get the time, I'd love to think about this more. But I'm also super aware of Warren Buffets advice that boils down to "If you don't know what you're doing, toss it in a low cost index fund like Vanguard and leave it there forever".
According to the stats on this blog close to 100 people drop by every day, most of you come from other personal finance blogs. I'd love to hear what you think (and verify that my stats aren't entirely robots!). The money hits my account on the 31st of March - what should I do with it?
Tuesday, 14 March 2017
How the Pink Tax is ruining your finances
Have you ever actually sat down and worked out how much it costs to be a presentable, functional human being. There's clothes, hair, make-up, hygiene, the inevitable caffeine hit to get you through the morning. Sometime in the past some smart marketing gurus figured out that if they make us feel bad about ourselves the way we are, they can sell us products to 'fix' ourselves.
And then they realised they could hit women twice as hard.
Some women are enamored with hair, make-up, nice clothes, nice shoes and will go the whole nine yards every day, whether they leave the house or not. Let's start by saying I'm not one of them. My makeup in high school was black eyeliner (as thick as it could go) and my hair was permanently in a pony tail. Unless I had just cut it in a vague attempt to be stylish, then I was just wishing for it to grow back.
But even with my minimal approach to hair and makeup, I was endlessly frustrated with how expensive everything was. And not just that it was expensive, but that it was more expensive for me than my partner. I once rang every single hair dresser within walking distance (I was young, I didn't have a car) and checked their pricing. On average to get a haircut was $40+. I then asked them how much it would be to get a haircut if I was male. If you're ever bored and want to make someone extremely uncomfortable, call a hairdresser and ask that question.
Me: "Hi, just wondering how much for a haircut?"
Bored sales voice "$40 for a style cut and blow dry"
Me: "Okay thanks, and how much if I was a bloke"
Very baffled person "... excuse me...?"
Me: "If I was male, how much would you charge me for a haircut?"
Extremely uncomfortable person "Oh, ermm, ahh. Mens cuts are $20"
Me, super chipper "Thanks! Have a nice day!"
It was half the price, just for being male, not just at one hairdresser, but consistently at every salon. This was when it was becoming quite common for women to have short hair (I like to call them 'Power Cuts') and men were having styled, sculpted hair. Without seeing me face to face there would have been no way for the person on the end of the phone to gauge the amount of time and effort my hair would cost, but because I was female they were willing to charge me significantly more.The same ridiculous costing applies across the board, anywhere a product can be classed male or female. A quick search of my local supermarket tells me that a 4 pack of womens razor blades is $17.60, while the same brand, same style for men is only $15.35. Identical toys for children could be priced higher merely for being pink, without any other differences.
In a popular Mr. Money Mustache post, he talks about the Universal Men's Grooming Device. While I love this post and all it entails, it frustrates me as just another example of Pink Tax. He recommends that all men toss away their razor blades, immediately cease visiting a hairdresser and pick up an electric razor for under $100. With the right attachments, this razor can be used for both facial hair and head hair and lasts for years. Which is amazing, especially when haircuts are $25 a pop. Except it's amazing for men. Women tend to be frowned upon when sporting a buzzcut.
Now this might seem like an entire post on social justice and a fair bit on whining on my part, but no one said you had to purchase the female version of things. It's just a giant marketing scam to try and tell you that your poor delicate female self needs special products. The fact is that you don't.
My partner and I signed up to the Dollar Shave Club. For $7 a month we received a fancy 4-blade razor, with 4 cartridges. After six months we had to cancel our subscription because we had too many blades. Even though we were both using them. And I have to say, after years of going through different brands of 'soft and smooth' women's razors, this is the best shave I've ever had. No Pink Tax, much higher quality.
The same goes for the soap, shampoo, moisturisers and haircuts in this house. I might have said above that buzz cuts on women are frowned upon, and I'm not saying you have to take the plunge with me but I love my buzz cut. I bought the fanciest set of clippers I could get for $100 when they were 50% off during the post-Christmas sales. They've served me faithfully for over a year when I first had an undercut and later moved to a full buzz cut. Since both my partner and I use them we've easily saved over $300 in haircuts in the first year alone.
If you don't want to join me in the buzz cut club (although I think every woman should try it once! such a liberating time-saver) the internet is full of tips and tricks for cutting your own hair. Sure you might not be able to manage the fancy layering technique your hairdresser uses, but if your hair lives in a ponytail anyway, you aren't missing out on much. Or maybe you could team up with a friend and learn together. No pressure, but if you give your bestie a bad haircut, you know she'll be the next one wielding the scissors!
Leave a comment and let me know what you're sick of paying the Pink Tax on. What tricks do you have? And guys, do you find yourself paying more for anything because it's "For Men"?
In a popular Mr. Money Mustache post, he talks about the Universal Men's Grooming Device. While I love this post and all it entails, it frustrates me as just another example of Pink Tax. He recommends that all men toss away their razor blades, immediately cease visiting a hairdresser and pick up an electric razor for under $100. With the right attachments, this razor can be used for both facial hair and head hair and lasts for years. Which is amazing, especially when haircuts are $25 a pop. Except it's amazing for men. Women tend to be frowned upon when sporting a buzzcut.
Now this might seem like an entire post on social justice and a fair bit on whining on my part, but no one said you had to purchase the female version of things. It's just a giant marketing scam to try and tell you that your poor delicate female self needs special products. The fact is that you don't.
My partner and I signed up to the Dollar Shave Club. For $7 a month we received a fancy 4-blade razor, with 4 cartridges. After six months we had to cancel our subscription because we had too many blades. Even though we were both using them. And I have to say, after years of going through different brands of 'soft and smooth' women's razors, this is the best shave I've ever had. No Pink Tax, much higher quality.
The same goes for the soap, shampoo, moisturisers and haircuts in this house. I might have said above that buzz cuts on women are frowned upon, and I'm not saying you have to take the plunge with me but I love my buzz cut. I bought the fanciest set of clippers I could get for $100 when they were 50% off during the post-Christmas sales. They've served me faithfully for over a year when I first had an undercut and later moved to a full buzz cut. Since both my partner and I use them we've easily saved over $300 in haircuts in the first year alone.
If you don't want to join me in the buzz cut club (although I think every woman should try it once! such a liberating time-saver) the internet is full of tips and tricks for cutting your own hair. Sure you might not be able to manage the fancy layering technique your hairdresser uses, but if your hair lives in a ponytail anyway, you aren't missing out on much. Or maybe you could team up with a friend and learn together. No pressure, but if you give your bestie a bad haircut, you know she'll be the next one wielding the scissors!
Leave a comment and let me know what you're sick of paying the Pink Tax on. What tricks do you have? And guys, do you find yourself paying more for anything because it's "For Men"?
Subscribe to:
Posts (Atom)
A quick 2023 check-in
I have been away for a tumultuous 12 months. I made a lot of changes. I changed career, I removed my birth control, and I very nearly ended...
-
I have been away for a tumultuous 12 months. I made a lot of changes. I changed career, I removed my birth control, and I very nearly ended...
-
May was a roller-coaster of a month. I got a dog, I gave back my dog, I had a huge burnout, and I pulled it all back together. My biggest ...